Five developments shaping business tax strategy for 2027
Five developments shaping business tax strategy for 2027
Follow FPA in Google
Get more timely tax insights from Freese, Peralez & Associates in Google Search.
Add FPA as a Preferred Source →FPA Executive Tax Brief™
Strategic Tax Intelligence for Growth-Focused Businesses
Issue No. 017 | Week of November 16–22, 2026
Estimated Reading Time: 10 Minutes
Executive Snapshot
Who Should Read This
- CEOs
- CFOs
- Controllers
- Construction Executives
- Manufacturing Leaders
- Real Estate Investors & Developers
- International Business Leaders
- Multi-Entity Business Owners
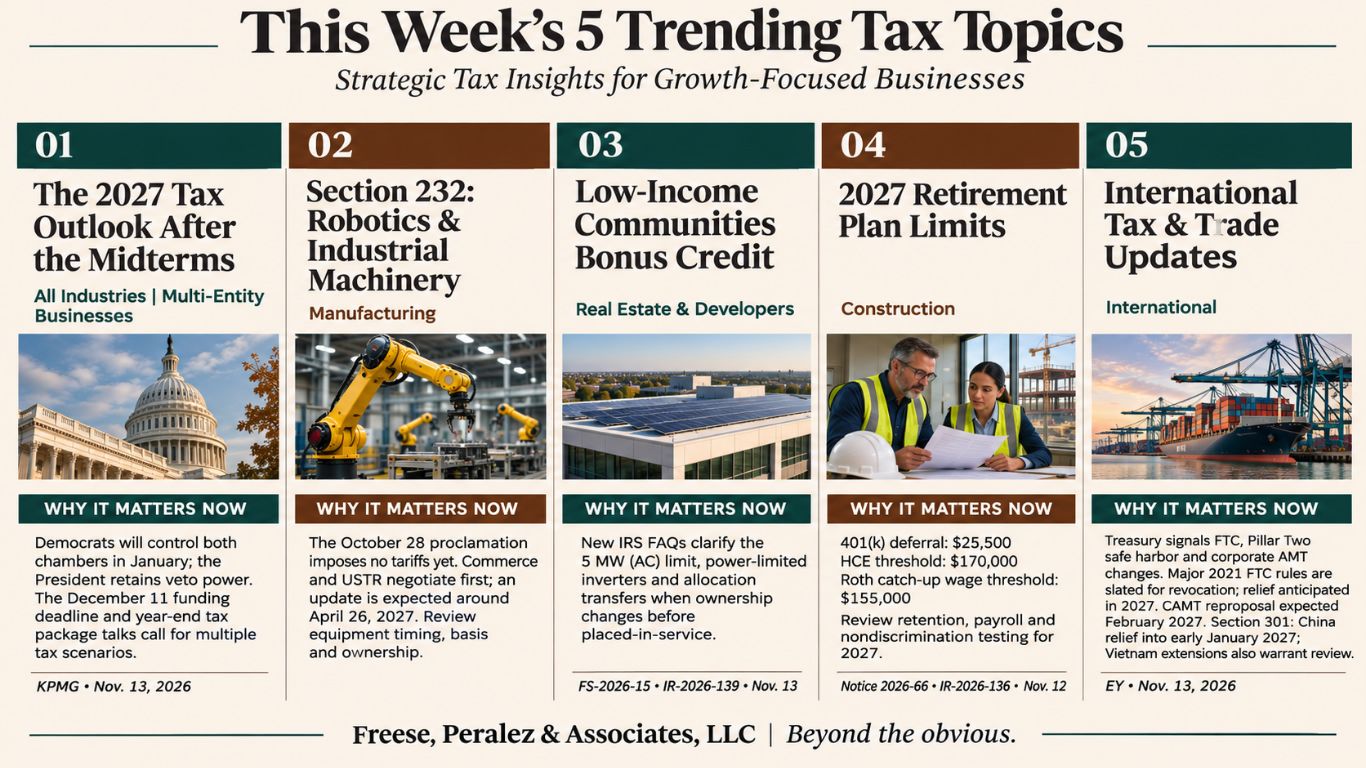
This Week at a Glance
| Development | Primary Industry | Priority |
|---|---|---|
| Post-Midterm 2027 Tax Planning Outlook | All Verticals / Multi-Entity Businesses | 🟡 Monitor / Consider Action |
| Section 232 Robotics and Industrial Machinery Proclamation | Manufacturing | 🟡 Consider Action |
| Low-Income Communities Bonus Credit Clarifications | Real Estate / Developers | 🔴 Immediate Review |
| 2027 Retirement Plan Contribution Limits | Construction | 🟡 Consider Action |
| International Tax Regulations and Section 301 Extensions | International / Manufacturing | 🟡 Monitor / Consider Action |
Weekly Executive Theme
Planning Through Uncertainty Without Standing Still
Businesses rarely have the luxury of making financial decisions with every variable resolved.
Equipment must be ordered before trade negotiations conclude.
Development projects must progress before every regulatory question is answered.
Employee compensation programs must be established before the next payroll year begins.
International operations must continue while tax authorities reconsider complex regulations.
And annual budgets must be finalized while Congress continues discussing legislation.
This week's developments illustrate the distinction between preparing for uncertainty and allowing uncertainty to delay important decisions.
Some of the changes are established requirements.
Others clarify existing rules.
Several represent developments that may influence future business costs but have not yet changed the law.
For executive leadership, effective planning begins with separating what is known, what remains unresolved, and which business decisions cannot reasonably wait.
Executive Overview
As businesses enter the final weeks of 2026, several developments deserve attention in their year-end and 2027 planning discussions.
The November midterm elections have changed the composition of the incoming Congress, while the December 11 government funding deadline remains an immediate legislative consideration.
Manufacturers evaluating automation and production equipment investments face continued uncertainty surrounding imported industrial machinery.
Real estate developers pursuing clean electricity incentives have new IRS guidance addressing technical eligibility requirements and ownership changes.
Construction employers preparing next year's compensation and benefits programs have updated retirement plan thresholds to incorporate into payroll and plan administration.
International businesses, meanwhile, are monitoring prospective foreign tax credit regulations, global minimum tax developments, corporate alternative minimum tax guidance, and temporary trade relief.
Each development operates on a different timeline.
Understanding those timelines and their relationship to existing business commitments is central to effective financial planning.
1. The 2027 Tax Outlook: Why Year-End Planning Should Include Multiple Scenarios
The November 3 midterm elections have established a different political environment for federal tax legislation beginning in January 2027.
According to KPMG's November 13 analysis, Democrats will control both chambers of the 120th Congress, while President Trump remains in office.
Legislation passed by Congress remains subject to presidential approval or the constitutional process for overriding a veto.
For business leaders, this creates an important distinction between legislative proposals and enacted tax law.
The Immediate Deadline Is December 11
Before the incoming Congress convenes, the current Congress must address the expiration of temporary government funding on December 11, 2026.
Discussions surrounding a potential year-end tax package are also continuing.
EY's November 13 legislative update identified possible areas of discussion, including certain expired tax incentives and proposed tax relief involving Taiwan.
However, discussions do not establish that these measures will become law.
Businesses should not assume that a potential tax extension, deduction, or other legislative provision will be available until the relevant legislation has been enacted.
Why Multi-Entity Businesses Need Scenario-Based Planning
A business operating through several entities may have different tax considerations at the corporate, partnership, and individual owner levels.
Financial models that rely on a single assumption about future tax policy may not fully reflect that complexity.
Consider a business group evaluating a significant expansion for 2027.
The organization may need to consider:
- The timing of capital expenditures
- Depreciation deductions
- Owner distributions
- Business interest expense
- The recognition of taxable income
- Available tax credits
- Financing arrangements
A practical financial model can establish a baseline using enacted law while separately illustrating the potential effects of specific legislative changes.
Separating the Budget From the Legislative Forecast
For financial leadership, three distinct planning scenarios may be useful:
Current-Law Scenario
The business prepares its financial projections using existing statutory provisions and applicable regulations.
Legislative-Change Scenario
Management evaluates how identified potential changes could affect taxable income, cash flow, and planned investments.
Delayed-Resolution Scenario
The organization considers the financial implications of continued legislative uncertainty, particularly where investment decisions or contractual commitments must proceed.
These scenarios are planning tools, not predictions about congressional action.
Questions Leadership Should Ask
- Which assumptions in our 2027 budget depend on legislation that has not been enacted?
- Have we established a current-law tax projection?
- Which potential tax changes would materially affect our organization?
- Are capital expenditures and owner distributions dependent on uncertain tax treatment?
- How would changes affect different entities within our ownership structure?
- Do our cash reserves accommodate a range of tax outcomes?
- Have we established a process for updating projections when legislation changes?
The election results establish a new legislative environment. They do not, by themselves, change the tax treatment of a business transaction.
2. Section 232: Manufacturers Face Continued Uncertainty Over Imported Robotics and Industrial Machinery
Manufacturers considering investments in automation, robotics, and production equipment should be aware of an October 28 presidential proclamation issued under Section 232 of the Trade Expansion Act of 1962.
The proclamation addresses imports of robotics, industrial machinery, and associated parts and components.
It follows a Department of Commerce investigation examining the national-security implications of these imports.
Importantly, the proclamation does not itself establish a new tariff on the covered products.
What the Proclamation Actually Does
The proclamation directs the Secretary of Commerce and the U.S. Trade Representative to pursue or continue negotiations with foreign trading partners.
Federal officials must provide a progress update within 180 days of the proclamation.
That places the reporting deadline on approximately April 26, 2027.
Depending on subsequent developments, additional measures could include tariffs, duties, quotas, fees, or incentives for domestic production.
None of those possible future measures should be treated as an established new import charge under the October 28 proclamation.
Why Equipment Investment Decisions Matter Now
Manufacturing equipment often involves significant lead times.
A company may order machinery months before delivery, installation, testing, and the commencement of production.
During that period, the financial assumptions supporting the investment may change.
Consider a manufacturer planning a $2 million investment in imported automated production equipment.
The initial purchase agreement may be based on the customs treatment in effect when the contract is signed.
If a new import duty becomes applicable before the equipment enters the United States, the project's total acquisition cost could increase.
Whether the manufacturer bears that additional cost will depend partly on the contractual allocation of import responsibilities.
The Relationship Between Import Costs and Tax Basis
Additional nonrecoverable import duties associated with acquiring capital equipment generally become part of the property's capitalized acquisition cost, subject to applicable tax rules.
That may increase the depreciable basis of the asset.
However, an additional depreciation deduction does not necessarily offset the immediate cash required to pay an import duty.
The business must evaluate both sides of the transaction:
- The additional acquisition cost
- The timing of the cash expenditure
- The resulting tax basis
- Available depreciation deductions
- The timing of equipment installation
- The project's expected operating return
As discussed in Issue 016, the 2027 Section 179 limits should also form part of this analysis, alongside available bonus depreciation and other applicable recovery provisions.
Ownership and Procurement Structure
Businesses operating through multiple entities should identify which company will purchase, import, own, and use the equipment.
Those roles may affect the applicable contractual responsibilities, tax treatment, financing arrangements, and depreciation analysis.
For manufacturers with international suppliers or related-party purchasing entities, coordination between procurement, finance, operations, and tax advisers is particularly important.
Questions Leadership Should Ask
- Which planned equipment purchases depend on imported machinery or robotics?
- Have the applicable customs classifications and existing duties been reviewed?
- When are the equipment orders expected to arrive?
- Who bears responsibility for additional import duties under our purchase agreements?
- How would higher acquisition costs affect projected returns and liquidity?
- Which entity will own and depreciate the equipment?
- Have we modeled alternative equipment sourcing and installation schedules?
A potential tariff is not yet an established cost, but understanding how that cost would affect capital investment decisions can improve financial preparedness.
3. Low-Income Communities Bonus Credit: Engineering Specifications and Ownership Can Determine Eligibility
Real estate developers incorporating clean electricity facilities into qualifying projects have additional IRS guidance to consider.
On November 13, the IRS announced Fact Sheet 2026-15 through news release IR-2026-139.
The guidance addresses the Low-Income Communities Bonus Credit Amount Program under Section 48E(h), with the individual FAQs dated November 16.
The program can increase the clean electricity investment tax credit by 10 or 20 percentage points, depending on the applicable project category and satisfaction of program requirements.
Eligibility involves an allocation process and is not established simply because a project is located in a qualifying community.
The 5 MW Requirement Is a Strict Threshold
An applicable facility must have a maximum net output of less than 5 megawatts, measured in alternating current (AC).
The IRS has clarified that a facility with a maximum net output of exactly 5 MW does not satisfy this requirement.
This distinction matters for developers and engineering teams evaluating energy systems near the eligibility threshold.
A relatively small difference in technical specifications could determine whether a facility satisfies the program's output requirement.
Permanently Power-Limited Inverters
The new guidance addresses circumstances in which an inverter's nameplate capacity indicates an output of 5 MW or greater, but the manufacturer has permanently limited its output.
For allocations beginning in 2026, such a facility may satisfy the output requirement when the applicant demonstrates that the manufacturer has permanently restricted the facility's maximum net output to below 5 MW (AC).
The limitation cannot simply be an adjustable operating preference.
The IRS identifies two possible forms of supporting documentation:
- Manufacturer certification establishing that the firmware restrictions are locked against adjustment by the owner and, where applicable, the operator.
- Professionally stamped engineering documentation certifying the permanent output restriction and applicable firmware protections.
This makes the engineering documentation an important component of the tax credit application.
Ownership Changes Before the Facility Is Placed in Service
The FAQs also address transactions involving facilities that have received an allocation but have not yet been placed in service.
An allocation award is associated with the taxpayer that applied for and received it.
If ownership changes before the facility is placed in service, the successor taxpayer must request an allocation transfer through the Applicant Portal.
Following IRS approval, the successor taxpayer must complete the applicable placed-in-service reporting.
The original owner cannot complete that reporting on the successor's behalf.
A transfer request may still be submitted after physical placement in service if ownership changed beforehand, the successor actually placed the facility in service, and the facility has not already been reported as placed in service through the portal.
Allocation transfers are permitted only between entities regarded separately for federal tax purposes.
Why Real Estate Ownership Structures Matter
Developers frequently separate property ownership, construction activities, energy infrastructure, and financing arrangements across different entities.
A project may also change ownership before construction is complete.
These transactions can create a disconnect between the original credit applicant and the taxpayer that ultimately owns and places the facility in service.
A projected tax credit should therefore be evaluated alongside the project's engineering specifications, ownership documents, allocation status, and reporting responsibilities.
The underlying Section 48E eligibility requirements and applicable statutory termination provisions must also be reviewed separately.
Questions Leadership Should Ask
- Does our project have a Low-Income Communities Bonus Credit allocation?
- Is the facility's maximum net AC output strictly below 5 MW?
- Are any inverter output restrictions permanent and properly certified?
- Has our engineering team provided the required supporting documentation?
- Which taxpayer received the original allocation award?
- Is a change in facility ownership anticipated before placement in service?
- Have allocation-transfer and reporting requirements been incorporated into the transaction documents?
- Does the financial model reflect all applicable Section 48E eligibility requirements?
A projected energy tax credit depends on more than project location. Engineering specifications, legal ownership, and administrative execution can determine whether the benefit is available.
4. 2027 Retirement Plan Limits: Construction Employers Have New Compensation Planning Considerations
On November 12, the IRS announced updated retirement plan contribution limits and related thresholds for 2027 through Notice 2026-66 and news release IR-2026-136.
For construction companies competing for experienced project managers, estimators, skilled tradespeople, and executive leadership, these adjustments deserve consideration during annual compensation and benefits planning.
Key Retirement Plan Thresholds for 2027
| Retirement Plan Provision | 2027 Amount |
|---|---|
| Standard 401(k) Employee Elective Deferral Limit | $25,500 |
| Highly Compensated Employee Compensation Threshold | $170,000 |
| Roth Catch-Up Prior-Year Wage Threshold | $155,000 |
The standard employee elective deferral limit increases by $1,000 from its 2026 level of $24,500.
However, the other two thresholds address different aspects of retirement plan administration and should not be confused with individual contribution limits.
The Highly Compensated Employee Threshold
The highly compensated employee, or HCE, classification is relevant to retirement plan nondiscrimination testing.
For certain retirement plans, the relationship between contributions made by highly compensated employees and other eligible employees affects compliance.
The compensation threshold is not the only factor used to determine HCE status.
Ownership and applicable lookback-year rules also matter.
Construction companies experiencing salary growth, management promotions, or ownership changes should coordinate their employee census information with their plan administrator.
The Roth Catch-Up Requirement
The Roth catch-up wage threshold addresses employees eligible to make catch-up contributions whose applicable prior-calendar-year wages exceed the indexed amount.
For affected employees, catch-up contributions generally must be made on a Roth basis.
The relevant wage measure generally involves prior-year Social Security wages from the employer sponsoring the plan, rather than total household income or compensation from unrelated employers.
For 2027 payroll administration, employers should evaluate applicable 2026 wages and ensure their systems correctly identify affected participants.
Why This Matters for Workforce Retention
A retirement plan is both a compliance responsibility and a component of the employer's total compensation offering.
Construction businesses often maintain diverse employee populations across field operations, administrative departments, management, and ownership.
Different employee groups may have different participation rates and contribution patterns.
Retirement plan design can therefore influence:
- Employee recruitment
- Management retention
- Compensation budgeting
- Employer matching costs
- Plan participation
- Nondiscrimination testing
- Payroll administration
A company preparing next year's labor budget should consider these factors together rather than treating the new contribution limit as an isolated payroll update.
Multi-Entity Considerations
Construction groups frequently operate through several related companies.
Where applicable, controlled-group and affiliated-service-group rules can affect retirement plan coverage and testing.
Separate payroll systems or separate legal entities do not necessarily establish that each company can be evaluated independently.
Ownership records and employee census information should be reviewed before the 2027 plan year begins.
Questions Leadership Should Ask
- Has our payroll provider incorporated the 2027 contribution limits?
- Have we reviewed highly compensated employee classifications?
- Which employees may be subject to mandatory Roth catch-up treatment?
- Can our payroll system identify affected employees using the appropriate prior-year wages?
- Do our retirement plan provisions accommodate the applicable contribution requirements?
- Are related entities being evaluated correctly for retirement plan purposes?
- Does our 2027 benefits budget reflect potential changes in contributions and employer matching costs?
Retirement plan administration is part of a broader workforce strategy. Updating payroll limits is necessary, but reviewing plan design, employee participation, and compliance is equally important.
5. International Tax and Trade: Treasury Signals Regulatory Changes While Section 301 Relief Remains Temporary
International businesses have several regulatory and trade developments to monitor as they prepare their 2027 financial projections.
EY's November 13 international tax update reported remarks from federal officials concerning foreign tax credits, Pillar Two global minimum tax compliance, and the corporate alternative minimum tax.
The update also addressed recent extensions involving Section 301 trade actions concerning China and Vietnam.
Although these developments affect different areas of cross-border business, they share an important characteristic: several remain subject to future regulatory or administrative action.
Foreign Tax Credit Regulations
According to EY's reporting, a senior Treasury official indicated that the government intends to withdraw substantial portions of the final foreign tax credit regulations issued in December 2021.
The rules have been subject to temporary relief since 2023.
Additional relief is anticipated in 2027, although the final scope and implementation remain unresolved.
One consideration identified by Treasury concerns the treatment of foreign digital services taxes.
For U.S. businesses operating internationally, the potential regulatory changes could affect whether particular foreign taxes qualify for U.S. foreign tax credits.
However, businesses should continue evaluating foreign taxes under the existing rules and applicable temporary relief until further guidance is issued.
Pillar Two Global Minimum Tax
Treasury officials also indicated support for additional Pillar Two safe harbors that would use existing taxpayer data or simplified calculations.
Such approaches could reduce compliance burdens for multinational groups subject to the global minimum tax framework.
The reported comments do not establish new safe harbors.
International groups should continue determining their obligations under the rules adopted by the jurisdictions in which they operate.
Although Pillar Two generally affects very large multinational groups, a smaller U.S. business may encounter related reporting requirements when it belongs to a larger foreign-parented organization.
Corporate Alternative Minimum Tax
Treasury officials indicated that reproposed corporate alternative minimum tax regulations remain anticipated for February 2027.
Potential revisions and transitional provisions are under consideration.
The federal corporate alternative minimum tax generally applies to certain large corporations based on adjusted financial statement income and applicable aggregation rules.
Many independently owned middle-market businesses will fall outside its direct application.
However, entities forming part of larger domestic or international corporate groups may need to consider whether group-level rules affect their position.
China Section 301 Relief
On November 10, the U.S. Trade Representative published notices continuing specified China-related Section 301 relief into early January 2027.
The extensions address certain product exclusions involving technology transfer and intellectual property measures, as well as the suspension of maritime, logistics, and shipbuilding actions.
These extensions are limited in scope.
They do not eliminate all Section 301 duties applicable to Chinese imports.
Importers should determine whether their particular products qualify for continued relief and consider the potential financial consequences of its expiration.
Vietnam Section 301 Investigation
The U.S. Trade Representative also extended its investigation into Vietnam's intellectual property protection and enforcement practices through February 28, 2027.
No additional tariff or other measure has yet been proposed under that particular investigation.
Other applicable duties and trade measures must be evaluated separately.
For businesses that have shifted sourcing to Vietnam, this distinction is important when assessing future supply-chain costs.
Why International Tax and Trade Planning Should Be Coordinated
A business may evaluate foreign tax credits through its tax department, customs exposure through its procurement department, and global minimum tax obligations through its parent company's finance team.
However, these responsibilities contribute to the organization's overall financial position.
Foreign tax credit availability can affect after-tax profitability.
Import duties can alter inventory and equipment costs.
Changes in global tax compliance requirements can influence administrative resources.
Coordinated financial modeling helps distinguish these exposures rather than treating every international development as a single tax issue.
Questions Leadership Should Ask
- Which foreign taxes are currently included in our U.S. foreign tax credit calculations?
- Does our organization rely on temporary foreign tax credit regulatory relief?
- Are we part of a multinational group subject to Pillar Two requirements?
- Could corporate alternative minimum tax aggregation rules affect our ownership structure?
- Which imported products currently benefit from China-related Section 301 exclusions?
- Have we modeled acquisition costs if temporary exclusions expire?
- Does our sourcing strategy account for the unresolved Vietnam investigation?
International tax planning depends on distinguishing current obligations from anticipated regulatory changes and temporary trade relief. Those distinctions should be reflected in financial projections.
Executive Perspective
This week's developments demonstrate why preparing for 2027 requires more than an updated tax estimate.
Legislative uncertainty creates a need for financial scenarios based on current law and identifiable potential changes.
Manufacturing investments require an understanding of existing import duties, contractual responsibilities, and equipment depreciation.
Real estate energy incentives depend on engineering specifications, ownership, and timely administrative compliance.
Retirement plan adjustments create new considerations for compensation budgets, employee classifications, and payroll systems.
International tax and trade developments require businesses to distinguish existing obligations from anticipated regulatory changes.
In each instance, uncertainty affects a different part of the organization's financial planning process.
But uncertainty does not prevent management from identifying exposure, improving documentation, and establishing appropriate financial controls.
A manufacturer can evaluate equipment acquisition costs before trade negotiations conclude.
A developer can verify inverter certifications before completing an energy project.
An employer can review retirement plan classifications before the next payroll year begins.
An international business can evaluate the expiration dates of temporary trade relief before committing to future purchases.
Effective tax planning does not require every future development to be resolved. It requires understanding which decisions can be made using the information available today.
That distinction becomes particularly important as businesses finalize their budgets and operating strategies for 2027.
Frequently Asked Questions
How do the 2026 midterm elections affect business tax planning for 2027?
The election results change congressional control beginning in January 2027 but do not automatically amend existing tax law. Any future legislative changes remain subject to the legislative process, including presidential approval or a successful veto override.
Did the October 28 Section 232 proclamation impose new tariffs on imported robotics?
No. The proclamation directs federal officials to pursue negotiations concerning imported robotics, industrial machinery, and their components, with a progress update required within 180 days. Additional trade measures remain possible but were not imposed by the proclamation itself.
Does a clean electricity facility with exactly 5 MW of output qualify for the Low-Income Communities Bonus Credit?
No. Section 48E(h) requires maximum net output below 5 MW (AC). Beginning with 2026 allocations, certain permanently manufacturer-limited inverters may satisfy the requirement when the facility's output is demonstrably restricted below that threshold and the applicable documentation requirements are met.
What is the 401(k) contribution limit for 2027?
The standard employee elective deferral limit for 2027 is $25,500, an increase from $24,500 in 2026. Separate catch-up contribution provisions may apply to eligible participants.
Has Treasury finalized new foreign tax credit regulations for 2027?
No. Treasury officials have indicated an intention to remove substantial portions of the December 2021 regulations and provide relief in 2027. The final regulatory changes and their implementation remain subject to future guidance.
About Freese, Peralez & Associates
Freese, Peralez & Associates is a tax-focused CPA firm located in The Woodlands, Texas, serving growth-focused businesses throughout Texas and across the United States.
We specialize exclusively in:
- Strategic Tax Planning
- Tax Consulting
- Business Tax Preparation
Our clients generally generate between $1 million and $100 million in annual revenue and frequently operate through multiple entities, across multiple states, or within increasingly complex domestic and international tax environments.
We work extensively with organizations in the construction, manufacturing, real estate development, and international business sectors.
Continue the Conversation
Preparing for a new tax year involves more than understanding the latest regulatory announcements.
It requires evaluating how those developments interact with the organization's investments, ownership structure, workforce, financial commitments, and long-term objectives.
For established businesses, the final weeks of 2026 provide an opportunity to review the assumptions supporting their 2027 financial plans.
If your organization is considering major equipment investments, managing complex development projects, reviewing employee compensation strategies, or operating across international markets, now may be an appropriate time to evaluate whether your tax strategy reflects both current requirements and emerging developments.
If you are not currently an FPA client, visit our Contact Us page and complete the form to schedule a confidential discovery call.
We would welcome the opportunity to learn more about your organization and determine whether proactive tax planning can help protect cash flow, preserve margins, and support your next stage of growth.
Coming Next Week
Our team continues monitoring:
- The December 11 federal government funding deadline
- Year-end tax legislation
- Section 232 industrial machinery negotiations
- Section 48E clean electricity investment credit guidance
- 2027 retirement plan administration
- Foreign tax credit regulatory developments
- Corporate alternative minimum tax guidance
- International trade and Section 301 relief
- Q4 and year-end planning opportunities
Because uncertainty is a normal part of doing business.
Preparing for it should be a normal part of your tax strategy.