5 developments shaping 2027 tax planning, documentation, and compliance
5 developments shaping 2027 tax planning, documentation, and compliance
Follow FPA in Google
Get more timely tax insights from Freese, Peralez & Associates in Google Search.
Add FPA as a Preferred Source →FPA Executive Tax Brief™
Strategic Tax Intelligence for Growth-Focused Businesses
Issue No. 016 | Week of November 9–15, 2026
Estimated Reading Time: 10 Minutes
Executive Snapshot
Who Should Read This
- CEOs
- CFOs
- Controllers
- Construction Executives
- Manufacturing Leaders
- Real Estate Investors & Developers
- International Business Leaders
- Multi-Entity Business Owners
This Week at a Glance
| Development | Primary Industry | Priority |
|---|---|---|
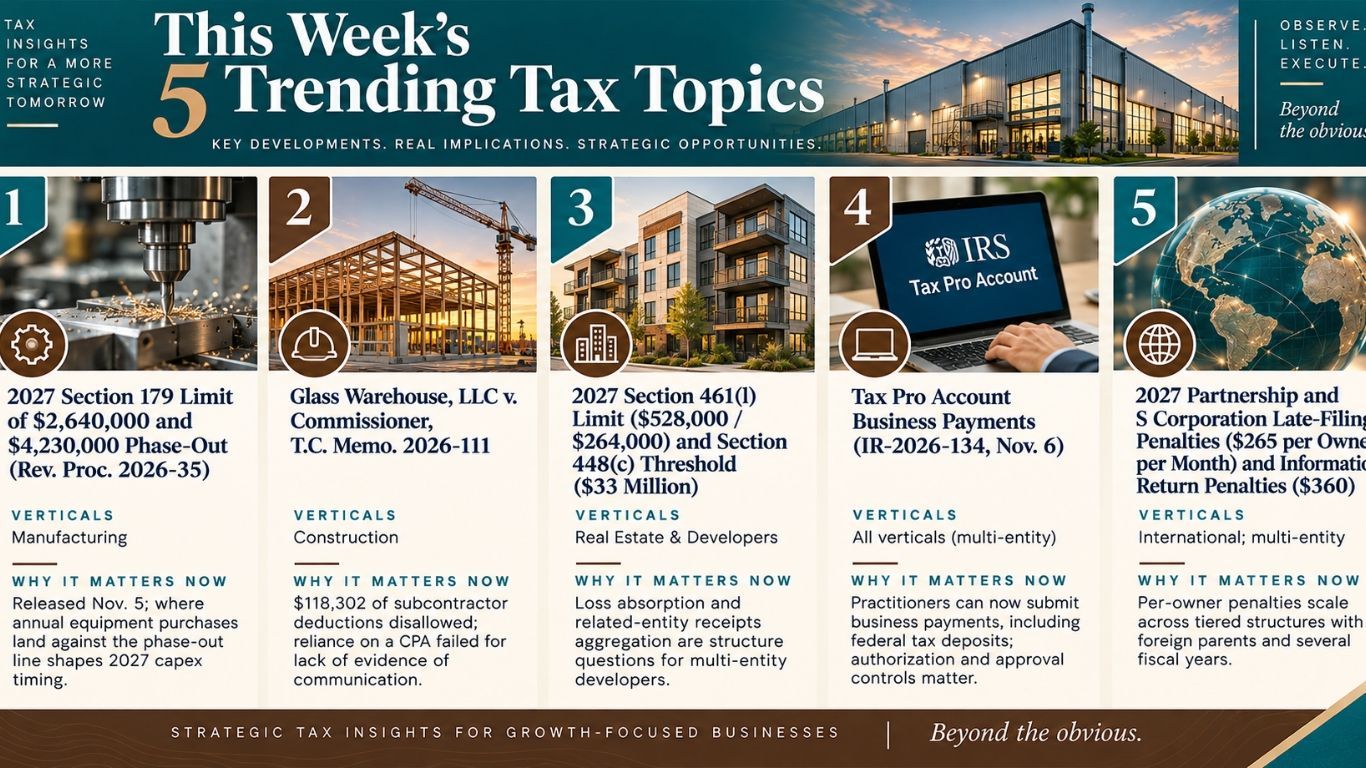
| 2027 Section 179 Expensing and Phase-Out Limits | Manufacturing | 🟡 Consider Action |
| Glass Warehouse Subcontractor Deduction Ruling | Construction / Closely Held Businesses | 🔴 Immediate Review |
| 2027 Excess Business Loss and Gross Receipts Thresholds | Real Estate / Developers | 🟡 Consider Action |
| IRS Tax Pro Account Business Payment Expansion | All Verticals / Multi-Entity Businesses | 🟡 Consider Action |
| Higher Partnership and Information Return Penalties | International / Multi-Entity Businesses | 🔴 Immediate Review |
Weekly Executive Theme
The Numbers Have Changed. Have Your Business Decisions?
Tax planning often begins with a number.
How much equipment can the business expense?
How much operating loss can an owner deduct?
How large can a business become before certain accounting rules change?
What is the penalty for filing late?
But knowing the number is only the beginning.
The more important question is how it interacts with the company's operations, ownership structure, cash flow, and documentation.
This week, the IRS released inflation-adjusted thresholds that will influence 2027 capital investment and tax planning.
The Tax Court also reinforced a different lesson: a deduction cannot be defended by bookkeeping labels or the existence of a CPA alone.
Meanwhile, the IRS expanded online payment functionality for authorized practitioners, and higher future filing penalties highlighted the financial consequences of administrative mistakes.
For CEOs and CFOs, these developments belong in the same conversation.
A strong tax strategy depends on more than knowing the rules. It requires financial decisions, supporting records, and internal controls that work together.
Executive Overview
The November 5 release of Revenue Procedure 2026-35 provides important figures for businesses planning their 2027 tax year.
Manufacturers now have updated Section 179 expensing and phase-out thresholds to incorporate into equipment budgets.
Real estate developers and owners of pass-through businesses must consider the interaction between excess business loss limits, entity-level income, and aggregated gross receipts.
A new Tax Court decision demonstrates why closely held businesses should document payments to owners with the same discipline applied to unrelated contractors.
The IRS has also expanded Tax Pro Account to permit authorized professionals to make certain payments for business clients.
Finally, increased penalties for returns required to be filed in 2028 create another reason for multi-entity organizations to strengthen their filing calendars and information-reporting procedures.
The common thread is execution.
The businesses best positioned to manage these developments are those that connect tax planning to budgeting, accounting, ownership records, and administrative controls before problems arise.
1. Section 179: New 2027 Limits Could Change Manufacturing Equipment Decisions
Manufacturers planning equipment purchases for 2027 now have updated federal expensing limits.
On November 5, the IRS released Revenue Procedure 2026-35, establishing the inflation-adjusted Section 179 amounts for tax years beginning in 2027.
The figures are significant:
- Maximum Section 179 deduction: $2,640,000
- Investment phase-out threshold: $4,230,000
- Maximum Section 179 amount for qualifying SUVs: $33,100
Section 179 generally allows qualifying businesses to elect to expense the cost of eligible property rather than recover that cost over multiple years through regular depreciation.
But the deduction is subject to limitations.
The Phase-Out Is Where Planning Becomes Important
For 2027, the maximum deduction is reduced dollar for dollar when the total cost of qualifying Section 179 property placed in service during the year exceeds $4,230,000.
Consider a simplified example.
A manufacturer places $4,500,000 of qualifying Section 179 property in service during 2027.
That amount exceeds the phase-out threshold by $270,000.
The maximum available Section 179 deduction would therefore decline from $2,640,000 to $2,370,000, before considering the taxable income limitation and other applicable rules.
The phase-out can eliminate the Section 179 deduction entirely when qualifying investment reaches $6,870,000.
This is particularly relevant for manufacturers making significant investments in production equipment, automation, or facility modernization.
Why Purchase Timing Matters
The relevant question is not simply when equipment is ordered or paid for.
Section 179 generally depends on qualifying property being placed in service during the applicable tax year.
A machine purchased in December but not ready and available for its intended use until January may belong in a different tax year's depreciation calculation.
That distinction can affect:
- Capital expenditure budgets
- Production expansion schedules
- Equipment installation timelines
- Cash-flow forecasts
- Financing decisions
- Taxable income projections
Section 179 Is Not the Only Depreciation Option
Manufacturers should also evaluate bonus depreciation and other applicable recovery provisions.
The most favorable immediate deduction is not necessarily the best overall tax strategy.
For example, a business may benefit from preserving deductions for future years, managing taxable income across multiple entities, or considering state depreciation differences.
Section 179 also has a business-income limitation that can restrict the amount currently deductible.
Questions Leadership Should Ask
- What equipment purchases are planned for 2027?
- How much qualifying property will be placed in service during the year?
- Will total investment exceed the $4,230,000 phase-out threshold?
- Have we compared Section 179 with bonus depreciation?
- Could equipment installation delays change the tax year of the deduction?
- Do projected taxable income and state rules affect the preferred approach?
- Has the tax team reviewed the capital expenditure budget before commitments are finalized?
The 2027 Section 179 limits create an opportunity to coordinate equipment investment with tax strategy—but the timing and total amount of qualifying purchases determine the result.
2. Glass Warehouse: $118,302 Deduction Denied as Documentation Falls Short
A recent Tax Court decision offers an important reminder for construction businesses and other closely held companies.
In Glass Warehouse, LLC v. Commissioner, T.C. Memo. 2026-111, filed November 2, 2026, the U.S. Tax Court disallowed a $118,302 deduction for purported subcontractor expenses.
The case also involved a separate accuracy-related penalty for an earlier tax year.
The dispute centered on payments associated with two shareholder-officers who already performed substantial services for the corporation as employees.
What Went Wrong?
The corporation reported compensation to its shareholder-officers and also claimed deductions for purported subcontractor services.
But the Court found that the company had not substantiated the additional services underlying the disputed deduction.
The record lacked persuasive evidence establishing the nature of the purported services, the contractual arrangements, and the basis for the amounts claimed.
The owners' reporting of payments on their personal returns did not establish the corporation's entitlement to deduct those amounts.
The Court did not need to resolve every possible alternative characterization of the payments.
Insufficient substantiation was enough to deny the deduction.
The CPA Reliance Defense Also Failed
The company separately challenged an accuracy-related penalty for an earlier year and argued that it had relied on its CPA.
But reasonable reliance on professional advice requires more than identifying a professional who prepared the return.
The taxpayer must establish relevant facts concerning the advice received and the information provided to the adviser.
The Court found the evidence insufficient to support that defense.
Why This Matters for Construction Businesses
Construction companies often use a mix of:
- Employees
- Independent subcontractors
- Owner-managers
- Related-party service companies
- Project-specific contractors
- Management and consulting arrangements
These relationships can be legitimate and commercially necessary.
However, the accounting treatment must reflect the underlying facts.
Payments to shareholder-employees deserve particular attention when the company also characterizes additional payments to those same individuals as contractor fees.
A deduction should be supported by records that establish what services were performed, why the payment was made, and how the amount was determined.
Documentation Should Be Built Into the Process
Depending on the arrangement, useful records may include:
- Written service agreements
- Invoices
- Scope-of-work descriptions
- Proof of payment
- Time and project records
- Required information returns
- Documentation of services beyond ordinary employee duties
- Written correspondence with tax advisers about the arrangement
No single document automatically guarantees deductibility.
The goal is to create a consistent record showing the economic substance of the transaction.
Questions Leadership Should Ask
- Are any owners receiving both employee compensation and contractor payments?
- Can we identify the specific services supporting each category of payment?
- Are related-party service arrangements documented?
- Do our accounting records reconcile to contracts, invoices, and payments?
- Are information-reporting obligations being met?
- Have significant tax positions been clearly communicated to our CPA?
- Could we produce the supporting evidence if the IRS examined the deduction several years from now?
A payment recorded as a business expense is not automatically a deductible business expense. The underlying services and supporting evidence matter.
3. 2027 Loss and Gross Receipts Thresholds: Why Real Estate Entity Structure Matters
For real estate developers and investors operating through partnerships, LLCs, and S corporations, Revenue Procedure 2026-35 contains two important sets of inflation-adjusted figures.
For tax years beginning in 2027:
- Section 461(l) excess business loss threshold: $528,000 for joint filers and $264,000 for other taxpayers
- Section 448(c) gross receipts threshold: $33 million
These provisions address different issues.
But both can become important when a business operates through multiple related entities.
Section 461(l): Business Losses May Be Limited at the Owner Level
Section 461(l) generally limits the amount of excess business losses that noncorporate taxpayers can deduct in a tax year.
For partnerships and S corporations, the limitation generally applies at the owner level.
This matters because a real estate investor may own interests in several operating or development entities.
One project may generate substantial deductions.
Another may produce taxable income.
A third may have losses subject to passive activity or other limitations.
The owner's final tax result depends on how those items interact under the applicable rules.
The Order of Limitations Matters
Section 461(l) does not operate in isolation.
Other limitations, including basis, at-risk, and passive activity rules, may apply first.
An investor cannot assume that a large partnership loss automatically becomes an immediately deductible personal tax loss merely because it falls within the excess business loss threshold.
Likewise, a loss limited under Section 461(l) may generally become part of a net operating loss carryforward under the applicable rules.
Section 448(c): Gross Receipts May Need to Be Aggregated
The $33 million threshold generally applies to the average annual gross receipts for the preceding three-tax-year period.
For certain accounting method provisions and other rules that reference Section 448(c), related entities may be required to aggregate gross receipts.
That means a developer cannot necessarily evaluate each LLC independently.
Consider a group with several commonly controlled operating companies.
Individually, each company may appear to fall below $33 million in average annual gross receipts.
But if the aggregation rules apply, the combined receipts may place the relevant businesses above the threshold.
The consequences can extend beyond the cash method of accounting because other tax provisions incorporate the Section 448(c) gross receipts test.
Why Developers Should Review Their Structures
Real estate groups often form separate entities for individual projects, properties, or business lines.
Those structures may serve legitimate legal, financing, and operational purposes.
But separate legal entities do not automatically mean separate tax thresholds.
Ownership relationships, controlled-group rules, and the nature of each business can influence the calculation.
Questions Leadership Should Ask
- What are the projected business losses for each owner in 2027?
- Have basis, at-risk, and passive activity limitations been considered?
- How will losses from different pass-through entities interact?
- Do we have a three-year gross receipts calculation for each relevant business?
- Are related entities required to aggregate receipts?
- Could crossing the $33 million threshold affect accounting methods or other tax provisions?
- Have ownership changes and newly formed entities been incorporated into the analysis?
For multi-entity real estate businesses, tax thresholds are not simply numbers assigned to individual LLCs. Ownership relationships and the owner's overall tax position can determine the result.
4. IRS Tax Pro Account Now Supports Business Payments: A New Control Point for CFOs
The IRS announced an expansion of Tax Pro Account on November 6, 2026.
Under the new functionality, authorized tax professionals can make certain federal tax payments on behalf of business clients through the secure online platform.
Previously, practitioners could view certain business account information but could not initiate these payments through Tax Pro Account.
The expansion adds another option for managing business tax obligations.
Which Payments Are Covered?
According to the IRS, authorized practitioners can now make payments involving:
- Full or partial account balances
- Amended returns
- Extensions
- Proposed tax assessments
- Federal tax deposits
The practitioner must have the appropriate authorization for the client and tax matters involved.
Why This Matters for Multi-Entity Businesses
A growing business may operate through several corporations, partnerships, and other entities.
Each may have separate federal tax accounts and payment obligations.
That creates an administrative challenge.
Payments must be applied to the correct:
- Taxpayer
- Employer identification number
- Tax type
- Tax period
- Liability
A payment made for the wrong entity or period can create avoidable reconciliation problems even when the organization has sufficient cash available.
Convenience Does Not Replace Oversight
The new functionality may improve efficiency, but it also makes internal approval procedures important.
A tax professional's ability to initiate a payment should not eliminate management's responsibility for reviewing and authorizing the amount.
For larger organizations, a practical payment-control process should identify:
- Who calculates the liability
- Who approves the payment
- Who initiates the transaction
- Who confirms that it posted correctly
- Who reconciles the payment to the general ledger
The appropriate division of duties will depend on the company's size and internal control environment.
Questions Leadership Should Ask
- Which tax professionals currently have authorization to act for our entities?
- Do we maintain an up-to-date record of those authorizations?
- Who approves business tax payments before submission?
- How are payment amounts, tax periods, and EINs verified?
- Are confirmations retained and reconciled?
- Does our existing payment process provide sufficient segregation of duties?
- Would the expanded Tax Pro Account functionality improve efficiency without weakening controls?
A more convenient tax payment process can reduce administrative friction—but only when authorization, approval, and reconciliation remain clearly defined.
5. Higher Filing Penalties Make Multi-Entity Compliance More Expensive
Revenue Procedure 2026-35 also establishes increased penalties for certain returns required to be filed in 2028.
For partnership and S corporation returns, the adjusted penalty is $265 per owner, per month or partial month, subject to the applicable statutory rules.
The general penalty for certain incorrect or late information returns increases to $360 per return, with different amounts for qualifying corrections and other circumstances.
These amounts are important for businesses with numerous entities and owners.
The Per-Owner Multiplier
The partnership and S corporation late-filing penalty is not a flat $265 charge.
The amount generally increases based on the number of partners or shareholders and the number of months—or partial months—the return remains late, up to the applicable 12-month maximum.
Consider a simplified example.
A partnership with 12 partners files a return three months late.
At the 2028 filing-year rate, the potential penalty would be:
$265 × 12 partners × 3 months = $9,540
Now consider a business group with several partnerships.
A filing failure affecting multiple entities can multiply the exposure.
The actual result depends on the applicable filing obligations, extensions, relief provisions, and facts.
Why International Structures Require Additional Attention
Internationally owned and multi-tiered organizations may have:
- U.S. partnerships
- S corporations where ownership is legally permitted
- Foreign-owned domestic entities
- Multiple fiscal-year reporting periods
- Related-party transactions
- International information returns
- Separate reporting deadlines
The filing requirements differ by entity type and ownership.
For example, S corporations generally cannot have nonresident alien shareholders or certain ineligible owners.
A foreign-parented group should not assume that every U.S. subsidiary is eligible for S corporation status.
International reporting failures may also trigger separate penalties not covered by the $265 and $360 figures.
Information Return Penalties
The $360 general amount applies to certain failures involving information returns required to be filed in 2028.
Lower amounts may apply when qualifying corrections are made within prescribed periods.
Other rules govern failures to furnish correct payee statements, intentional disregard, and particular return types.
This makes timely reconciliation of vendor, owner, and payee information especially important.
Questions Leadership Should Ask
- Do we maintain a complete filing calendar for every entity?
- Are fiscal-year and calendar-year filing obligations tracked separately?
- Who is responsible for extensions?
- Are ownership changes communicated to the tax team promptly?
- Are partnership and shareholder counts accurate?
- Have international information-reporting obligations been identified?
- Are Forms 1099 and other information returns reconciled before filing?
- Is there a documented process for reviewing and correcting filing errors?
For multi-entity businesses, a missed filing deadline is rarely just an administrative inconvenience. The number of entities and owners can turn a small error into a significant penalty.
Executive Perspective
This week's developments illustrate two sides of tax management.
The first is opportunity.
Higher Section 179 limits may influence manufacturing investment decisions.
Updated business loss and gross receipts thresholds may change how owners evaluate deductions and accounting methods.
The second is protection.
The Glass Warehouse decision shows the importance of supporting deductions with credible evidence.
Expanded IRS payment capabilities create opportunities for efficiency while increasing the importance of payment controls.
And higher filing penalties reinforce the need for accurate entity records and coordinated compliance.
For CEOs and CFOs, these are not separate conversations.
Capital investment, tax planning, entity structure, accounting records, and internal controls all contribute to the same financial outcome.
A business can identify a valuable deduction and still lose it because the records do not support the claim.
It can have adequate cash to pay its taxes and still encounter problems because a payment is misapplied.
It can operate through legally separate entities and still face tax rules requiring combined analysis.
The strongest tax strategy connects the numbers to the decisions, documentation, and controls that make those numbers meaningful.
That is the difference between simply preparing for tax season and preparing the business for what comes next.
Frequently Asked Questions
What is the Section 179 deduction limit for 2027?
For tax years beginning in 2027, the maximum Section 179 deduction is $2,640,000. The deduction begins to phase out when qualifying Section 179 property placed in service exceeds $4,230,000, subject to other applicable limitations.
Why did the Tax Court deny the deduction in Glass Warehouse?
The Court found that the corporation failed to substantiate $118,302 in purported subcontractor expenses. The disputed payments involved shareholder-officers, and the company did not provide sufficient evidence of the additional services supporting the deduction.
What are the 2027 Section 461(l) and Section 448(c) limits?
For tax years beginning in 2027, the excess business loss threshold is $528,000 for joint filers and $264,000 for other taxpayers. The Section 448(c) average annual gross receipts threshold is $33 million, subject to applicable aggregation rules.
Can a CPA now make federal tax payments for a business client through Tax Pro Account?
Yes. As of November 6, 2026, the IRS permits appropriately authorized tax professionals to make certain business payments through Tax Pro Account, including federal tax deposits, extension payments, and payments toward account balances.
What is the new partnership late-filing penalty?
For partnership returns required to be filed in 2028, the inflation-adjusted penalty is $265 per partner for each month or partial month the return is late, subject to applicable limitations and reasonable-cause relief. The same adjusted per-owner amount applies to certain S corporation filing failures.
About Freese, Peralez & Associates
Freese, Peralez & Associates is a tax-focused CPA firm located in The Woodlands, Texas, serving growth-focused businesses throughout Texas and across the United States.
We specialize exclusively in:
- Strategic Tax Planning
- Tax Consulting
- Business Tax Preparation
Our clients generally generate between $1 million and $100 million in annual revenue and frequently operate through multiple entities, across multiple states, or within increasingly complex domestic and international tax environments.
We work extensively with organizations in the construction, manufacturing, real estate development, and international business sectors.
Continue the Conversation
The latest tax thresholds and procedural developments create important questions for established businesses.
How should equipment investments be timed?
Are payments to owners properly documented?
Do related entities need to be evaluated together?
Are tax payments subject to appropriate approval controls?
And could a missed filing deadline expose multiple entities to unnecessary penalties?
These questions are best addressed before they become problems.
If your organization is planning major capital investments, operating through multiple entities, managing related-party payments, or preparing for a more complex 2027 tax year, now may be an appropriate time to evaluate whether your tax strategy reflects the latest developments.
If you are not currently an FPA client, visit our Contact Us page and complete the form to schedule a confidential discovery call.
We would welcome the opportunity to learn more about your organization and determine whether proactive tax planning can help protect cash flow, preserve margins, and support your next stage of growth.
Coming Next Week
Our team continues monitoring:
- 2027 tax inflation adjustments
- Section 179 equipment expensing
- Business expense substantiation and Tax Court decisions
- Excess business loss and gross receipts thresholds
- IRS Tax Pro Account capabilities
- Partnership and S corporation filing penalties
- Manufacturing and construction tax developments
- Multi-entity and international tax compliance
- Q4 and year-end planning opportunities
Because knowing the numbers is only the beginning.
The real value comes from making the right decisions around them.