5 Tax Decisions Before Year-End
5 Tax Decisions Before Year-End
Follow FPA in Google
Get more timely tax insights from Freese, Peralez & Associates in Google Search.
Add FPA as a Preferred Source →FPA Executive Tax Brief™
Strategic Tax Intelligence for Growth-Focused Businesses
Issue No. 012 | Week of October 12–18, 2026
Estimated Reading Time: 9 Minutes
Executive Snapshot
Who Should Read This
- CEOs and CFOs
- Controllers and Tax Directors
- Construction and Manufacturing Executives
- Real Estate Investors and Developers
- International Business Leaders
- Multi-Entity Business Owners
This Week at a Glance
| Development | Primary Industry | Priority |
|---|---|---|
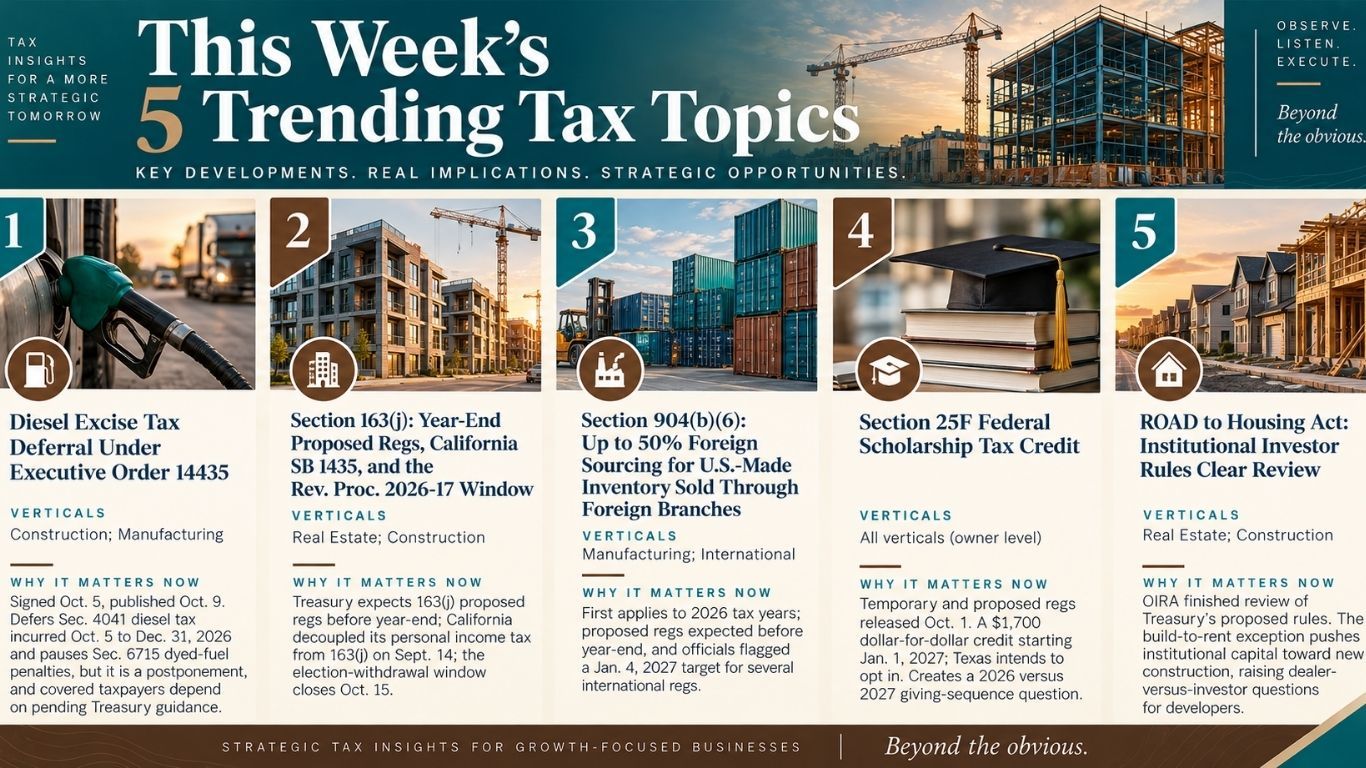
| Diesel Excise-Tax Deferral Under Executive Order 14435 | Construction / Manufacturing | 🔴 Immediate Review |
| Section 163(j) Election Withdrawal and State Differences | Real Estate / Construction | 🔴 Immediate Review |
| Section 904(b)(6) Foreign Tax Credit Sourcing | Manufacturing / International | 🟡 Consider Action |
| Section 25F Scholarship Tax Credit | Business Owners / All Verticals | 🟢 Monitor / Plan |
| ROAD to Housing Act Investor Restrictions | Real Estate / Construction | 🟡 Consider Action |
Weekly Executive Theme
The Rules Are Changing. The Planning Windows Are Narrowing.
There is a meaningful difference between tax relief being announced and a business being eligible to use it.
That distinction runs through all five developments this week.
A federal order may postpone certain diesel excise-tax obligations, but postponement is not forgiveness.
A more favorable business interest-expense limitation may make an old real estate election worth reconsidering, but transitional withdrawal procedures have deadlines.
A new foreign tax credit sourcing provision may improve the treatment of qualifying U.S.-manufactured inventory, but the result depends on how the taxpayer earns and sources its income.
A new scholarship credit begins in 2027, making the timing of charitable contributions relevant today.
And federal housing legislation is changing the framework for institutional investment in single-family homes, while important implementing rules are still emerging.
The opportunity is not simply understanding what changed. It is identifying which decisions can still be made before the rules or deadlines narrow the options.
Executive Overview
As businesses enter the final quarter of 2026, tax planning is increasingly intersecting with operational decisions.
Fuel purchasing and fleet operations may be affected by temporary federal excise-tax relief.
Real estate groups with significant debt may need to revisit previous Section 163(j) elections before an applicable transition window closes.
U.S. manufacturers selling products through foreign branches may have a new opportunity to improve foreign tax credit calculations.
Business owners considering charitable contributions have a new federal scholarship credit to evaluate for 2027.
And residential developers are facing an evolving investment environment as Treasury prepares implementation rules for restrictions on large institutional purchases of existing single-family homes.
These developments do not affect every business equally.
But they reinforce a common principle:
The tax implications of an operating decision should be understood before the decision becomes difficult to reverse.
1. Diesel Excise-Tax Relief: A Cash-Flow Opportunity, Not a Tax Repeal
On October 5, Executive Order 14435, Emergency Tax Relief on Diesel Fuel, directed Treasury to provide temporary relief involving certain federal diesel fuel excise taxes.
The order was published in the Federal Register on October 9.
Among its provisions, it directs Treasury to exercise available authority to postpone payment obligations involving qualifying Section 4041 diesel fuel taxes incurred from October 5 through December 31, 2026.
It also directs the IRS to announce temporary relief from specified Section 6715 penalties involving dyed diesel fuel sold for highway use or used on highways during that period.
The distinction between these provisions matters.
A Deferral Is Not Forgiveness
The order does not itself permanently eliminate the underlying tax.
It directs Treasury to establish implementing guidance identifying:
- Which taxpayers qualify
- Which taxes and liabilities are covered
- Which deadlines are postponed
- Applicable conditions and geographic or operational limitations
- When postponed amounts must ultimately be paid
For construction companies and manufacturers, this creates a potential cash-flow planning issue rather than an automatic tax saving.
Businesses should avoid treating deferred amounts as permanent reductions in fuel expense or tax liability.
Why This Matters Operationally
Fuel costs affect more than transportation.
For construction companies, diesel is a significant input for equipment, generators, fleet vehicles and job-site operations.
Manufacturers may also face substantial fuel costs through their own fleets, logistics arrangements and equipment.
However, Section 4041 does not apply identically to every diesel purchase or user. The taxpayer legally responsible for the excise tax and the type of fuel transaction are important.
A business buying ordinary highway diesel at retail should not assume that it can independently defer an excise tax imposed elsewhere in the distribution chain.
Questions Leadership Should Ask
- Which entities in our organization are actually liable for Section 4041 taxes?
- Does Treasury's implementing guidance cover our transactions?
- Are fuel suppliers adjusting invoices or payment terms?
- How will any deferred liability appear in our Q4 cash forecast?
- What records distinguish taxable highway use from other fuel uses?
- Are we maintaining reserves for taxes that remain payable later?
Temporary fuel-tax relief may improve near-term liquidity, but only for qualifying taxpayers—and only if the deferred liability is properly managed.
2. Section 163(j): A More Favorable Federal Rule Creates New Election Questions
The business interest-expense limitation remains one of the most important provisions for debt-intensive companies.
For tax years beginning after December 31, 2024, the OBBBA restored depreciation, amortization and depletion add-backs when calculating adjusted taxable income under Section 163(j).
That change generally makes the federal interest-deduction limitation more favorable for many leveraged businesses.
For real estate developers and construction companies, however, the more significant planning issue may involve an election made years earlier.
Should a Previous Real Estate Election Be Reconsidered?
Certain real property trades or businesses may elect out of Section 163(j).
That election generally requires the use of the Alternative Depreciation System for specified property and can restrict bonus-depreciation benefits.
When the federal interest limitation was less favorable, electing out may have appeared attractive.
But with the restored adjusted-taxable-income calculation and other depreciation changes, the economics may now be different.
Revenue Procedure 2026-17 provides transitional procedures for qualifying taxpayers seeking to withdraw certain prior elections.
An October 15 procedural date may be particularly important for affected taxpayers, although the exact eligibility and filing requirements depend on the taxpayer's circumstances.
The State Tax Complication
Federal and state treatment may not produce the same answer.
California's September 2026 legislative changes illustrate the need to review state conformity and decoupling rules independently.
A business may obtain one result under the federal Section 163(j) calculation and a different result for state income-tax purposes.
For multi-state operators, that makes an election-withdrawal analysis more complicated than comparing federal interest deductions alone.
Questions Leadership Should Ask
- Did any of our entities previously elect out of Section 163(j)?
- How much additional federal interest capacity exists under the restored calculation?
- Would withdrawing an election change depreciation treatment?
- Does Revenue Procedure 2026-17 provide an available withdrawal procedure?
- Are any applicable October 15 requirements approaching?
- How do California and other state rules affect the overall benefit?
- Have projected financing and capital expenditures been incorporated?
A prior tax election should not remain untouched simply because it was appropriate under an older version of the law.
3. Section 904(b)(6): A New Foreign Tax Credit Opportunity for U.S. Manufacturers
For manufacturers producing goods in the United States and selling them internationally, one of the less-publicized OBBBA changes deserves attention.
New Section 904(b)(6) can permit qualifying taxpayers to treat up to 50% of certain income from inventory produced in the United States and sold through foreign branches as foreign-source income for foreign tax credit limitation purposes.
The provision applies beginning with tax years after December 31, 2025.
This is not a blanket rule allowing every U.S. exporter to reclassify half of its income.
The benefit depends on qualifying inventory, foreign branch activity and the applicable sourcing and foreign tax credit rules.
Why Sourcing Matters
The foreign tax credit generally helps prevent qualifying foreign income from being taxed twice.
But the amount of credit available is subject to limitations.
Those limitations depend partly on how much taxable income is treated as foreign-source income within the applicable foreign tax credit category.
A U.S. manufacturer may pay foreign taxes while still having income treated as U.S.-source under existing inventory sourcing rules.
That can create unused foreign tax credits.
Section 904(b)(6) may improve the calculation for qualifying transactions.
The Structural Question
Consider a U.S. manufacturer that produces equipment domestically but distributes and sells it through a foreign branch.
The company may have significant foreign sales and foreign taxes.
Whether Section 904(b)(6) improves its foreign tax credit position depends on the precise structure and the income attributable to qualifying inventory sales.
This makes the rule particularly relevant when businesses are evaluating:
- Foreign branch operations
- International distribution models
- Inventory production locations
- Foreign tax credit carryovers
- Cross-border expansion
- Foreign sales profitability
Additional Treasury guidance is expected, making documentation and modeling especially important.
Questions Leadership Should Ask
- Do we manufacture qualifying inventory in the United States?
- Are sales conducted through foreign branches?
- How is income from those sales currently sourced?
- Do we have unused or limited foreign tax credits?
- Would the new sourcing rule improve credit utilization?
- Are our foreign branch and inventory records sufficient to support the calculation?
- Should proposed regulations affect how we structure future international sales?
For qualifying manufacturers, where inventory is produced and how it is sold internationally can influence the value of foreign tax credits.
4. Section 25F: A New Federal Scholarship Credit Creates a 2027 Giving Decision
On October 1, Treasury and the IRS released temporary and proposed regulations implementing the new federal scholarship tax credit under Section 25F.
Beginning with qualifying contributions in 2027, eligible individual taxpayers may claim a nonrefundable federal income-tax credit of up to $1,700 annually for contributions to qualifying scholarship granting organizations.
The credit is designed to support eligible elementary and secondary education scholarships.
For business owners, the most relevant issue is not simply the credit amount.
It is the timing and structure of personal charitable giving.
A Credit Is Different From a Deduction
A qualifying tax credit generally reduces federal income tax dollar for dollar, subject to applicable limitations.
A charitable deduction reduces taxable income.
Those mechanisms can produce very different outcomes.
But the Section 25F credit has important restrictions.
For example:
- Contributions must satisfy the statutory and regulatory requirements.
- The scholarship granting organization must qualify under the program.
- State participation matters.
- State tax credits for the same contribution can reduce the federal credit.
- A taxpayer cannot claim both the Section 25F credit and a federal charitable deduction for the same qualifying contribution.
- Unused credits may be eligible for carryforward under the statutory rules.
The proposed regulations also explain requirements for scholarship granting organizations and participating states.
The 2026 Versus 2027 Question
For business owners who regularly support educational charities, timing could matter.
A contribution made during 2026 generally cannot qualify for a Section 25F credit that begins with qualifying contributions in 2027.
That does not automatically mean postponing charitable giving is the best decision.
The comparison depends on the donor's current and future tax situation, the recipient organization's eligibility, applicable state participation and the other charitable-giving rules.
Texas has expressed an intention to participate, but donors should verify the applicable state election and approved scholarship granting organizations before assuming a particular contribution qualifies.
Questions Leadership Should Ask
- Are we planning significant personal charitable contributions before year-end?
- Do any intended recipients qualify—or expect to qualify—as scholarship granting organizations?
- Would a 2027 credit provide a different result than a 2026 deduction?
- Are there state credits that could reduce the federal benefit?
- Are the applicable state and organization approvals complete?
- How does the contribution fit into the owner's broader personal tax strategy?
The new scholarship credit creates a planning opportunity, but the timing of a gift and the eligibility of its recipient determine whether the credit is available.
5. ROAD to Housing Act: Institutional Investor Rules Could Reshape Residential Development
The 21st Century ROAD to Housing Act establishes new restrictions on certain large institutional investors purchasing single-family homes.
The framework generally targets investors owning more than 350 single-family homes, subject to statutory definitions, exemptions and implementing rules.
The restrictions are scheduled to take effect in January 2027.
Treasury submitted its first proposed implementing rule for regulatory review in early October, and that review was completed October 9.
However, completion of the review does not mean the proposed regulations are final or that their full contents are publicly available.
The Build-to-Rent Question
One of the most important issues for real estate developers involves build-to-rent communities.
The law includes an exception for qualifying build-to-rent activity, but its practical boundaries will depend on statutory requirements and implementation.
For developers, the distinction between acquiring existing single-family homes and developing qualifying new rental housing can materially affect transaction strategy.
Institutional capital may evaluate:
- New construction
- Build-to-rent communities
- Joint ventures
- Development financing
- Property disposition strategies
- Holding periods
- Portfolio acquisitions
The rules could also influence which buyers are available when a development reaches completion.
Where Tax Strategy Enters the Conversation
The housing legislation does not itself resolve whether a developer's property is held primarily for sale or investment under federal income-tax rules.
That classification depends on separate tax principles and the facts of the activity.
However, changing investment structures or exit strategies may make those questions more important.
For example, a developer shifting from building homes for sale to operating a rental portfolio may need to revisit assumptions concerning:
- Dealer versus investor classification
- Inventory versus depreciable property
- Entity structure
- Financing
- Holding periods
- Gain characterization
- Depreciation and disposition planning
These are not automatic consequences of the ROAD to Housing Act.
They are potential tax implications of business decisions made in response to the new investment environment.
Questions Leadership Should Ask
- Do our investment partners fall within the large institutional investor definition?
- Are planned acquisitions affected by the new restrictions?
- Does our build-to-rent strategy satisfy the statutory exception?
- Could proposed regulations change transaction documentation requirements?
- Are our project exit assumptions dependent on institutional purchasers?
- Would a shift from sales to long-term rental operations change the property's tax treatment?
- Should pending transactions be reviewed before the January 2027 effective date?
The real estate opportunity is not simply identifying an exemption; it is understanding how changing investment structures may affect the entire project lifecycle.
Executive Perspective
This week's developments illustrate why tax strategy must be connected to business strategy.
A diesel-tax deferral is relevant only if the company qualifies and manages the future liability.
Section 163(j) relief becomes valuable when financing, depreciation and prior elections are evaluated together.
Foreign tax credit sourcing can change the economics of U.S. manufacturing and international distribution.
The scholarship credit creates a new personal planning consideration for business owners.
And institutional housing restrictions can influence investment structures and development exits, with corresponding tax implications.
In every case, the technical rule is only part of the analysis.
The more important question is how the rule affects decisions that are being made today.
The strongest tax planning does not wait for every deadline to become urgent. It identifies the decision window while leadership still has options.
Frequently Asked Questions
Does Executive Order 14435 eliminate federal diesel fuel excise taxes?
No. The order directs Treasury to provide temporary relief involving certain Section 4041 diesel fuel taxes incurred from October 5 through December 31, 2026. The underlying tax is not automatically forgiven, and implementing guidance determines the applicable relief and payment requirements.
Can a real estate business withdraw a previous Section 163(j) election?
Certain qualifying taxpayers may be eligible to withdraw prior real property trade or business elections under transitional procedures, including Revenue Procedure 2026-17. Eligibility, timing and the consequences for depreciation must be reviewed individually.
What is Section 904(b)(6)?
Section 904(b)(6) provides a special foreign tax credit sourcing rule that can allow qualifying income from certain U.S.-produced inventory sold through foreign branches to be treated as foreign-source income, subject to applicable requirements and limitations.
When does the Section 25F scholarship tax credit begin?
The federal scholarship tax credit applies to qualifying contributions beginning in 2027. Eligible individual taxpayers may receive a nonrefundable credit of up to $1,700 annually, subject to statutory requirements and participating-state and organization rules.
Does the ROAD to Housing Act ban all institutional investment in single-family homes?
No. The law targets certain large institutional investor purchases and contains exceptions, including qualifying build-to-rent activity. The scope and implementation of those restrictions require review of the statute and forthcoming regulations.
About Freese, Peralez & Associates
Freese, Peralez & Associates is a tax-focused CPA firm located in The Woodlands, Texas, serving growth-focused businesses throughout Texas and across the United States.
We specialize exclusively in:
- Strategic Tax Planning
- Tax Consulting
- Business Tax Preparation
Our clients generally generate between $1 million and $100 million in annual revenue and frequently operate through multiple entities, across multiple states, or within increasingly complex domestic and international tax environments.
We work extensively with organizations in the construction, manufacturing, real estate development and international business sectors.
Continue the Conversation
The difference between knowing a tax rule and benefiting from it often comes down to timing, eligibility and implementation.
For established businesses, those questions can influence cash flow, capital investment, financing decisions, international operations and long-term growth.
If your organization is managing significant equipment and fuel costs, carrying substantial business debt, expanding internationally or evaluating real estate investment structures, now is an appropriate time to determine whether your tax strategy reflects the latest developments.
If you are not currently an FPA client, visit our Contact Us page and complete the form to schedule a confidential discovery call.
We would welcome the opportunity to learn more about your business and determine whether proactive tax planning can help protect cash flow, preserve margins and support your next stage of growth.
Coming Next Week
Our team continues monitoring:
- Treasury implementation of diesel excise-tax relief
- Section 163(j) regulations and election procedures
- Foreign tax credit sourcing guidance
- Section 25F scholarship credit implementation
- ROAD to Housing Act proposed regulations
- Manufacturing and construction tax developments
- International business tax planning
- Q4 and year-end planning opportunities
Because the announcement is only the beginning.
The details determine what the business can actually do.