Nexus Tax Exposure
Nexus Tax Exposure
Nexus Tax Exposure: The Hidden Risk of Growing Across State Lines
As companies expand across state lines, tax obligations can be triggered without physical presence. Under current rules, revenue alone may create nexus, exposing businesses to multi-state filings, penalties, and audits. A proactive nexus strategy can reduce risk and optimize tax outcomes.
What is nexus tax exposure?
Nexus tax exposure occurs when a business has sufficient economic or operational activity in a state to create a tax obligation even without a physical presence. This can trigger filing requirements, taxes owed, and potential penalties if not properly managed.
Growth across state lines creates opportunity.
It also creates tax exposure often before leadership realizes it.
For mid-market companies, nexus is no longer tied to physical presence.
It’s tied to revenue, activity, and economic presence.
What Changed: The Post-Wayfair Reality
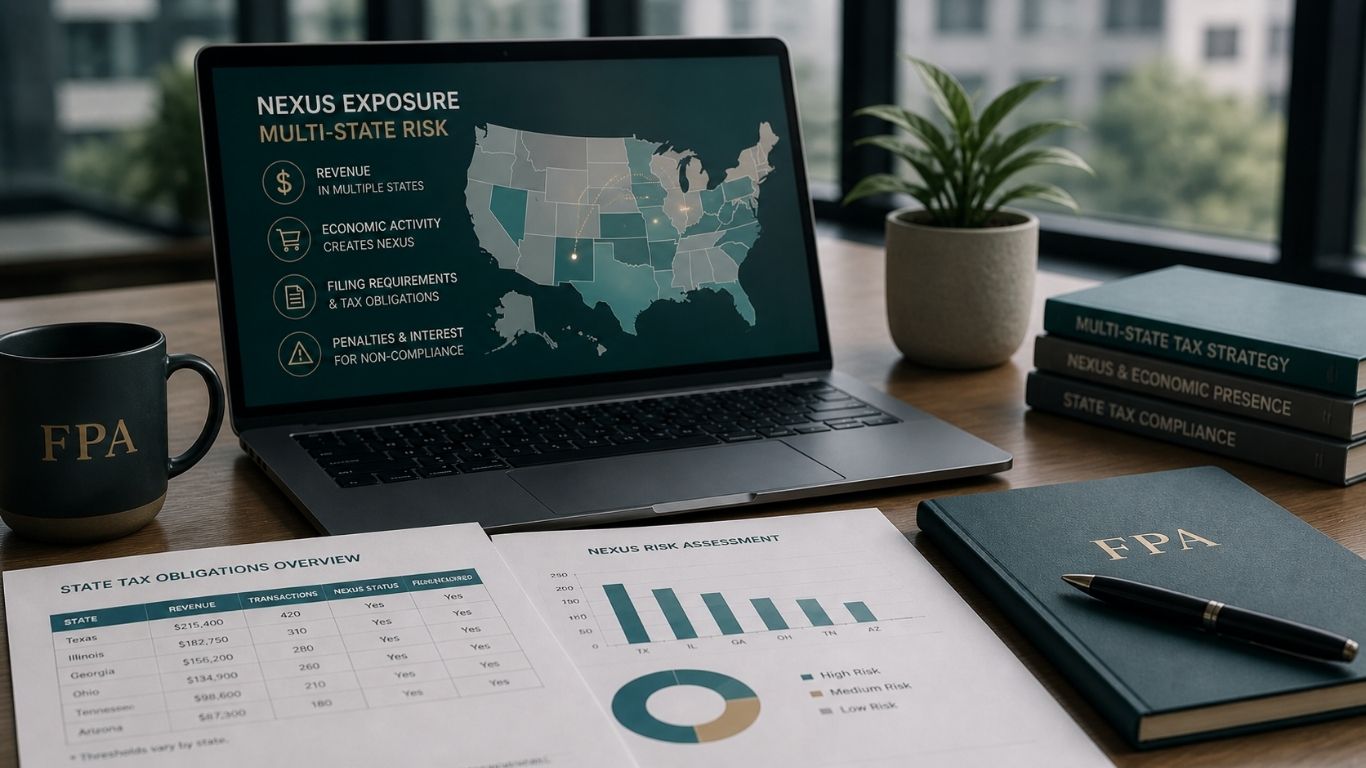
The South Dakota v. Wayfair, Inc. decision fundamentally changed how states enforce nexus.
Most states now impose economic nexus thresholds, typically:
- $100,000 in revenue
- 200 transactions
This means businesses can trigger tax obligations without:
- Offices
- Employees
- Inventory
Revenue alone is often enough.
What Triggers Nexus in Multiple States?
Many companies assume nexus only applies when they “set up shop” in a new state.
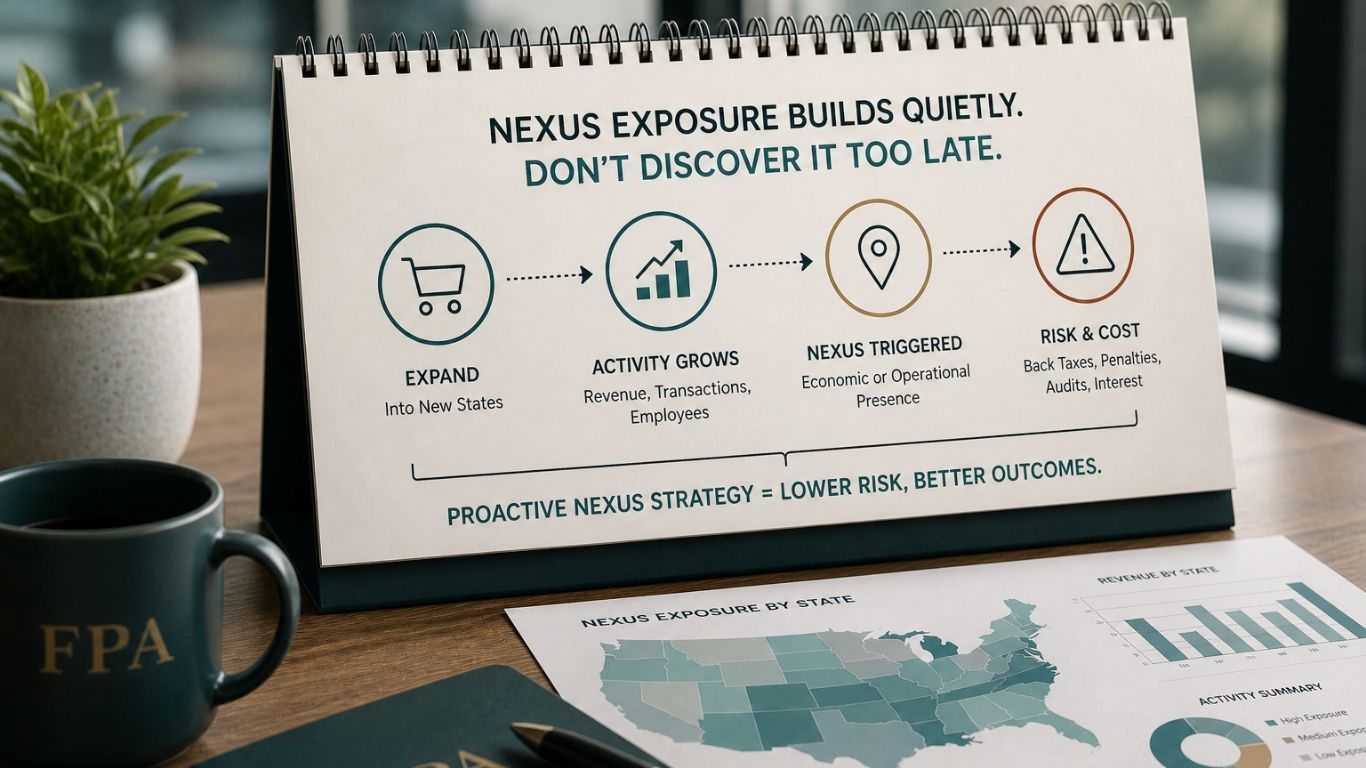
In reality, exposure often builds quietly through:
- Selling into new states (even remotely)
- Hiring remote employees or contractors
- Expanding service or delivery areas
- Operating through multiple entities
These activities can create nexus long before leadership identifies the risk.
Where Companies Get Caught
The most common issue isn’t creating nexus it’s not realizing it early enough.
By the time exposure is identified:
- Multiple years of filings may be required
- Back taxes may be owed
- Penalties and interest may apply
In some cases, this also opens the door to state-level audits.
Why Nexus Tax Exposure Matters
Unmanaged nexus doesn’t just create compliance issues it impacts financial performance.
Common consequences include:
- Multi-state filing requirements
- Penalties and interest
- Audit exposure
- Increased effective state tax rates
- Unexpected administrative burden
For growing companies, this can quickly become a material issue.
The Strategic Opportunity Most Companies Miss
Nexus is not just a compliance issue.
It’s a strategic planning lever.
With proper structuring, companies can:
- Optimize apportionment across states
- Manage overall state tax burden
- Align operations with more favorable tax jurisdictions
- Plan entity structure more effectively
Filing everywhere is compliance. Structuring it properly is strategy.
When Should You Conduct a Nexus Review?
You should consider a formal nexus review if your company:
- Has expanded into new states within the last 1–3 years
- Has remote employees or distributed teams
- Generates revenue across multiple states
- Has never completed a structured multi-state tax review
The Bottom Line
If your company has grown across state lines and hasn’t completed a structured nexus review, there is a strong likelihood of:
- Hidden tax exposure
- Missed planning opportunities
Addressing nexus proactively allows you to reduce risk and make more informed decisions as your business continues to grow.
If your business operates across multiple states and you’re unsure whether your current structure is optimized, we can help you evaluate your exposure and identify opportunities to improve your tax position.
FAQs
What is nexus in state taxes?
Nexus is the level of connection between a business and a state that creates a tax obligation, such as filing returns or paying taxes.
What triggers economic nexus?
Economic nexus is typically triggered when a business exceeds a state’s revenue or transaction threshold, often $100,000 in sales or 200 transactions.
Can you have nexus without a physical presence?
Yes. After the South Dakota v. Wayfair, Inc. decision, businesses can create nexus based on revenue alone.
What happens if nexus is not addressed?
Unmanaged nexus can result in back taxes, penalties, interest, and potential audit exposure.