R&D Tax Credit Explained: How Mid-Market Companies Capture More
R&D Tax Credit Explained: How Mid-Market Companies Capture More
The R&D Tax Credit: A Systematic Approach to Capturing a Benefit Most Companies Underutilize
Why So Many Companies Miss It
Many leadership teams assume R&D credits apply only to:
- Pharmaceutical research
- University-sponsored lab experiments
- Patent-driven innovation
That’s outdated thinking, the statutory threshold is not “invention.” It is systematic experimentation to eliminate technical uncertainty. And that happens far more frequently than most CFOs realize.
If your engineering team is solving technical problems, you may be generating R&D credits.
What Qualifies: The Four-Part Test
To qualify under IRC §41, activities must satisfy four elements:
Business Component
The work must relate to developing a new or improved:
- Product
- Process
- Software
- Technique
- Formula
- Invention
It does not need to be revolutionary it needs to be technical and forward-looking.
Technological in Nature
The activity must rely on principles of:
- Engineering
- Computer science
- Physics
- Chemistry
- Biology
Business process redesign alone does not qualify. Technical redesign does.
Process of Experimentation
The company must evaluate alternatives through:
- Modeling
- Iteration
- Testing
- Prototyping
- Refinement
Documented problem-solving is central.
Elimination of Technical Uncertainty
The objective must be to eliminate uncertainty related to:
- Capability
- Method
- Design
Resolving market uncertainty does not qualify. Resolving “Can this design achieve required tolerance?” often does.
The bar is structured experimentation not scientific breakthrough.
Where the Credit Is Actually Built: Qualified Research Expenses (QREs)
The R&D credit is calculated based on four primary categories of expenditures:
1️⃣ Wages
Compensation paid to employees:
- Directly performing qualified research
- Supervising research
- Supporting research
For many companies, wages represent the largest credit driver.
2️⃣ Supplies
Materials consumed during prototype testing or development efforts.
3️⃣ Contract Research
65% of amounts paid to qualified third-party contractors conducting eligible research activities.
4️⃣ University Research (Limited Applications)
Payments for certain basic research collaborations.
For manufacturing and engineering firms, the wage base, particularly for process engineers, design engineers, and technical supervisors, is often substantial but untracked.
Most underutilized credits stem from uncaptured engineering wages.
The Alternative Simplified Credit (ASC): Practical and Accessible
The R&D credit can be calculated under:
- The Regular Credit Method
- The Alternative Simplified Credit (ASC)
For most mid-market companies, the ASC method is preferable.
The ASC equals:
14% of qualified research expenses exceeding 50% of the average QREs from the prior three tax years.
Why it often makes more sense:
- No 1984–1988 base period reconstruction
- Reduced historical record burden
- More predictable modeling
For companies experiencing growth in engineering headcount or product lines, the ASC frequently produces meaningful credit while minimizing administrative burden.
The ASC makes the R&D credit practical for modern mid-market companies.
Manufacturing Applications: Beyond the Lab
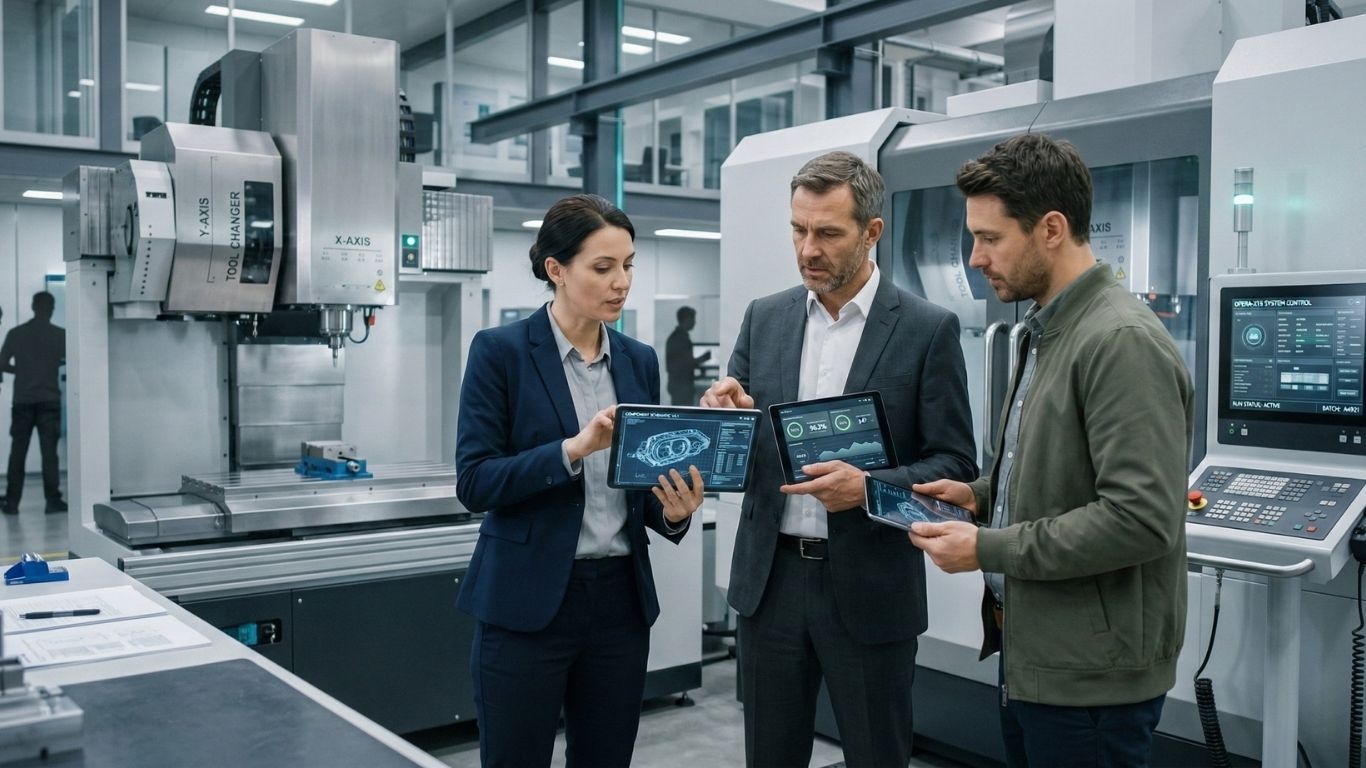
Manufacturers often under-claim the r and d credit because research activity is categorized operationally rather than technically.
Common qualifying activities include:
- Designing new production processes
- Improving manufacturing yield
- Testing alternative materials
- Tooling design for new product lines
- Automation engineering
- Quality control process refinement
The process engineer optimizing tolerance standards may generate as much qualifying activity as the product development team.
But if time tracking does not distinguish development from routine production, the credit is lost.
Process improvement frequently qualifies even when it isn’t labeled “R&D.”
Technology & SaaS: Software Development Credits
For technology companies, qualifying activities commonly include:
- Development of new platform functionality
- Architectural redesign to increase scalability
- API infrastructure engineering
- Algorithm development
- Iterative testing cycles
Customer-facing development almost always qualifies when technical uncertainty exists.
Internal-use software is more restrictive and must satisfy the high-threshold-of-innovation test, meaning substantial risk and innovation beyond routine business functions.
Proper time tracking and project documentation are typically the largest barriers to capturing the full credit.
Documentation discipline determines credit size more than technical activity alone.
The Cash Flow Impact
For qualifying mid-market companies, a properly supported R&D credit study frequently produces:
- $50,000
- $100,000
- $250,000
- Or $500,000+
In annual federal credits, depending on engineering headcount and scope. Credits directly reduce tax liability dollar-for-dollar. They are not deductions. They are tax offsets.
Additionally, credits may:
- Offset payroll taxes for certain emerging companies
- Carry forward to future tax years
The return on a properly executed study often materially exceeds the compliance investment.
Building a Systematic Capture Process
The highest-performing organizations approach R&D credits as a system, not a once-every-few-years event.
A strong framework includes:
- Quarterly identification of qualifying projects
- Engineering team interviews
- Time-tracking refinement
- Contemporaneous documentation
- Alignment between finance and technical leadership
The goal is not “find credit.” The goal is "build defensible support."
The most valuable R&D credits are the ones you can defend.
The Bottom Line
The R&D tax credit is permanent.
It is not a temporary incentive.
Companies solving technical problems daily especially in manufacturing, SaaS, and applied engineering all often qualify without realizing it.
If you have not conducted a structured R&D credit review in the last two years, the credit you are leaving unclaimed may materially exceed the cost of evaluating eligibility.
We are happy to discuss how your technical operations align with current R&D credit standards and whether you are capturing everything the law permits.