Multi-State Tax Strategy for CFOs Managing Growing Operations
Multi-State Tax Strategy for CFOs Managing Growing Operations
Navigating Multi-State Tax Exposure: A Strategic Framework for CFOs Managing Operations Across Jurisdictions
The expansion of economic nexus standards following the Supreme Court’s 2018 decision in South Dakota v. Wayfair fundamentally altered the state tax landscape.
Five years later, many organizations are still operating with compliance systems designed for a pre-Wayfair world.
For CFOs overseeing $30M to $100M enterprises operating across jurisdictions, multi-state tax management is no longer a back-office issue.
It is a margin protection issue.
A cash flow issue.
A risk exposure issue.
And, when handled strategically, it can be a competitive advantage.
Economic Nexus: Beyond Physical Presence
Before 2018, physical presence largely determined whether a company needed to collect sales tax or file income tax returns in a state.
Employees. Offices. Inventory.
That framework no longer defines exposure.
Today, most states impose sales tax collection requirements once a company exceeds economic thresholds, commonly:
- $100,000 in annual in-state sales, or
- 200 separate transactions
Income tax nexus standards are evolving more gradually but are moving in the same direction. Several states apply factor-presence nexus rules based solely on revenue thresholds, even absent physical presence.
For multi-state operators, especially manufacturers, distributors, and construction companies bidding across state lines, this creates silent exposure risk.
Growth across markets can create filing obligations before leadership realizes it.
Revenue growth can trigger state tax liability even without boots on the ground.
The Apportionment Opportunity
Nexus determines where you must file.
Apportionment determines how much of your income is taxed there.
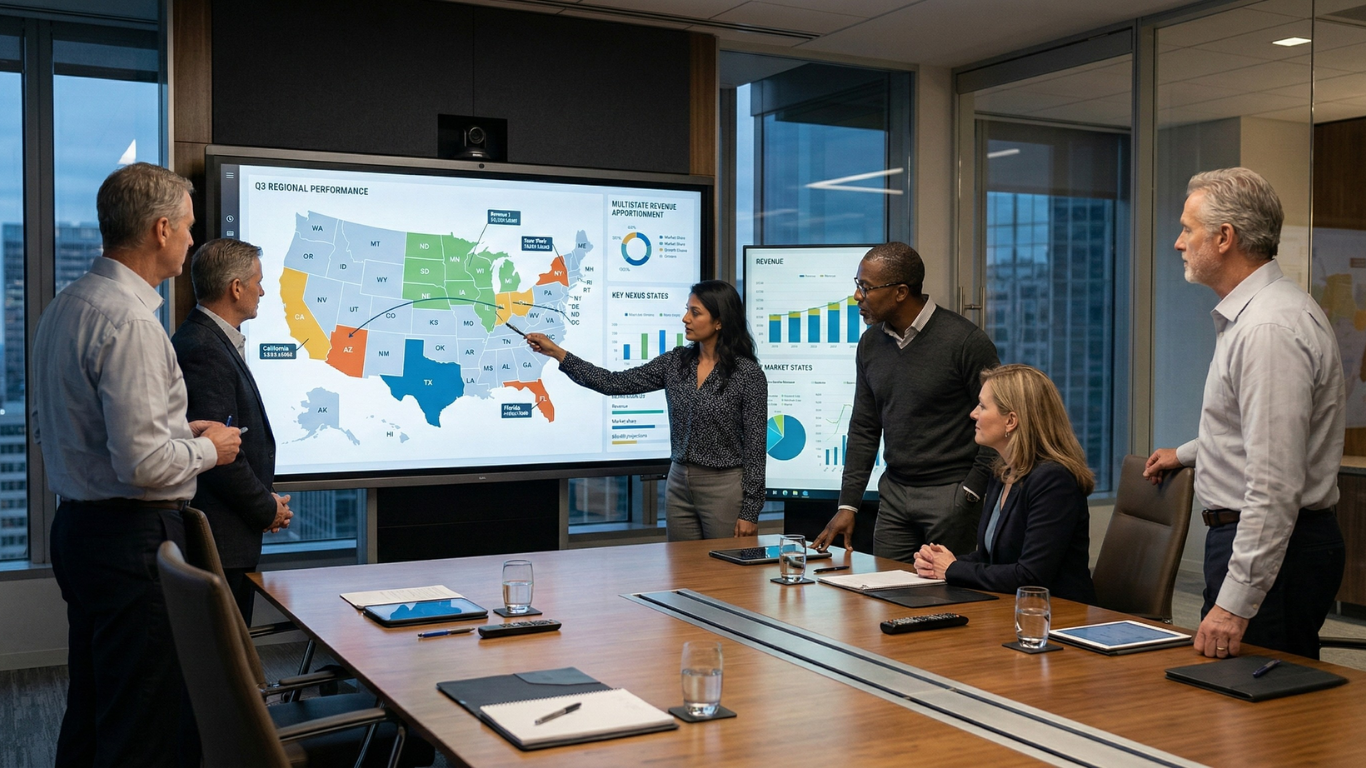
Most states now use a single sales factor apportionment formula meaning the percentage of sales into a state drives the allocation of taxable income.
That shift can create both risk and opportunity.
For example:
- A company producing goods in a low-tax state but selling heavily into a high-tax state may have meaningful income exposure.
- Conversely, a capital-intensive manufacturer with production facilities in one state and diversified national sales may benefit from thoughtful sourcing analysis.
For construction companies, revenue sourcing rules can vary depending on whether states use market-based sourcing or cost-of-performance standards.
Without modeling apportionment, CFOs are reacting to filings rather than managing effective state tax rate.
Filing everywhere is compliance. Managing apportionment is strategy.
Voluntary Disclosure: Clearing Exposure Before It Becomes an Audit
When a nexus review identifies prior-year exposure, the response determines financial outcome.
Most states offer voluntary disclosure agreements (VDAs) that:
- Limit lookback periods (commonly three to four years)
- Waive penalties
- Provide structured compliance entry
However, VDAs must generally be initiated before the state contacts the taxpayer.
Once an audit notice arrives, negotiating leverage changes.
For CFOs overseeing growing enterprises, conducting periodic nexus studies and evaluating VDA eligibility is not an admission of error, but structured risk containment.
Addressing exposure proactively is almost always less expensive than waiting for enforcement.
Transfer Pricing and Related-Party Transactions
Multi-entity structures particularly among manufacturers with distribution entities or IP holding companies introduce state-level transfer pricing scrutiny.
While federal transfer pricing standards are widely recognized, several states impose:
- Related-party add-back statutes
- Royalty expense disallowance rules
- Intercompany management fee scrutiny
Absent adequate documentation and defensible pricing methodology, states may disallow deductions increasing taxable income at the subsidiary level.
This is especially relevant in single-sales-factor states where income shifting strategies may not operate as originally modeled.
Multi-state transfer pricing should be evaluated alongside:
- Federal documentation standards
- State-specific add-back rules
- Audit defensibility
Intercompany planning that works federally may fail at the state level without documentation.
Remote Work: The Quiet Nexus Creator
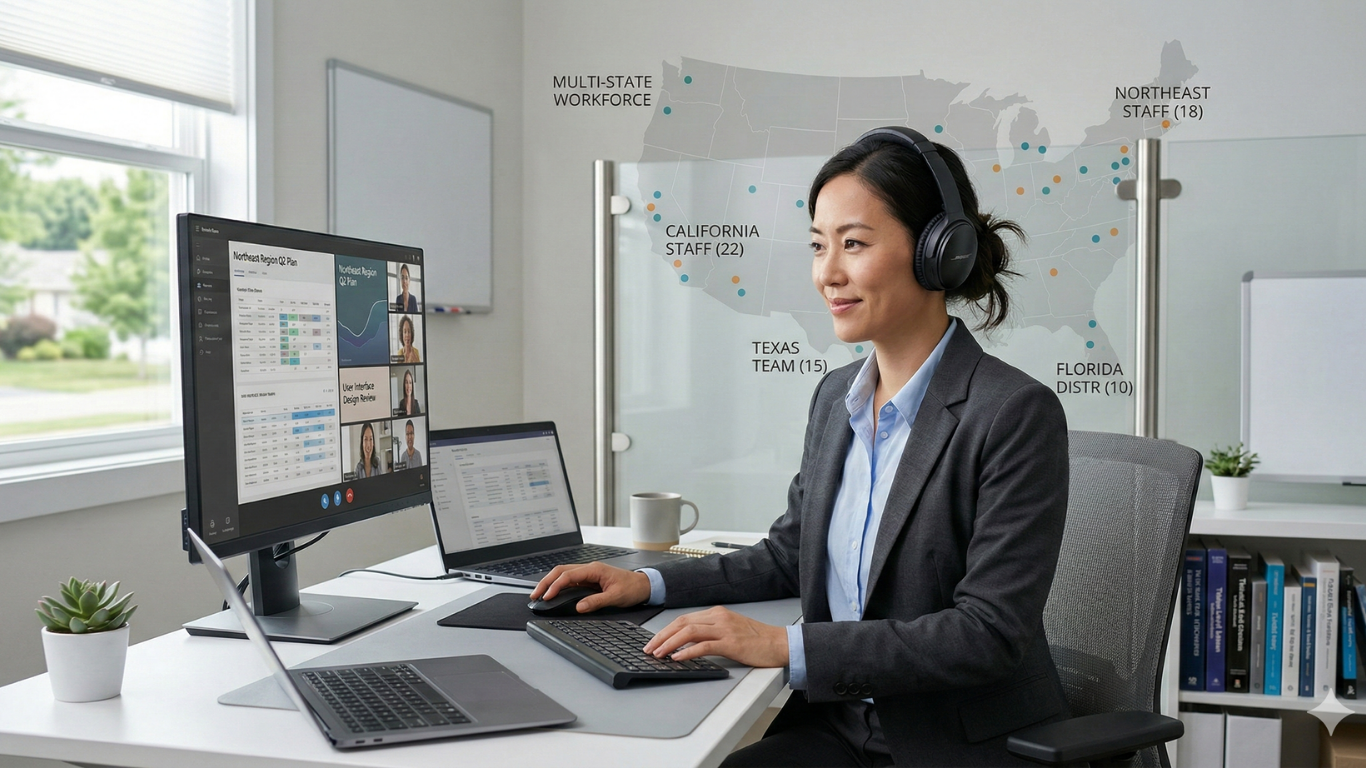
The normalization of remote and hybrid work arrangements has reshaped state tax exposure.
An employee residing and working remotely in a state where the company has no other presence may create:
- Income tax nexus
- Payroll withholding obligations
- Unemployment tax liability
State-specific rules govern whether withholding follows the employee’s residence or physical work location.
For organizations with distributed workforces across multiple states, a payroll nexus audit should be routine especially as workforce models evolve.
Overlooking remote payroll exposure is one of the most common multi-state compliance blind spots in mid-market organizations.
Remote employees create tax footprints even when your office footprint has not changed.
Building a Strategic Multi-State Framework
High-performing CFOs treat multi-state tax as an ongoing strategic discipline, not an annual reporting exercise.
A structured framework typically includes:
- Annual nexus reviews
- Apportionment modeling
- Related-party documentation assessment
- VDA eligibility evaluation
- Payroll nexus monitoring
- Legislative change tracking
The expansion of state enforcement mechanisms and inter-state data sharing increases visibility for revenue departments.
Organizations that treat multi-state tax management reactively often incur:
- Avoidable penalties
- Interest exposure
- Audit disruption
- Margin compression
Those that treat it strategically consistently protect enterprise value more effectively.
Multi-state tax exposure compounds quietly, until it doesn’t.
The Bottom Line
Operating across jurisdictions introduces complexity but complexity can be modeled.
CFOs who proactively evaluate nexus exposure, apportionment strategy, related-party planning, and payroll implications position their organizations for sustainable growth without unnecessary state tax leakage.
If your organization has not completed a structured multi-state review in the last 24 months particularly following post-Wayfair expansion and workforce shifts, that review is likely overdue.
We are happy to discuss how your current state tax footprint aligns with your operational growth trajectory.